Winter is coming, and the energy scramble is back. If you thought European industry had permanently adapted to post-crisis gas realities, look closer at the docks. Supplies from the Persian Gulf remain severely constrained, storage caverns sit below historical averages, and buyers in Tokyo, Seoul, and Beijing are quietly bidding up spot cargoes. Europe is bracing for a high-stakes tug of war with Asia over liquefied natural gas, and the pricing pressure is already showing up on screens from Amsterdam to Singapore.
European benchmark gas prices hover near €72 per megawatt-hour after recent volatility driven by shifting diplomatic signals over the Strait of Hormuz. When tankers can't freely clear major chokepoints, the global energy map redraws itself overnight. Traders aren't panicking quite yet, but everyone remembers the summer spikes when Asian spot prices touched $70 per million British thermal units. That kind of capital muscle pulls floating supply away from European terminals faster than you can blink.
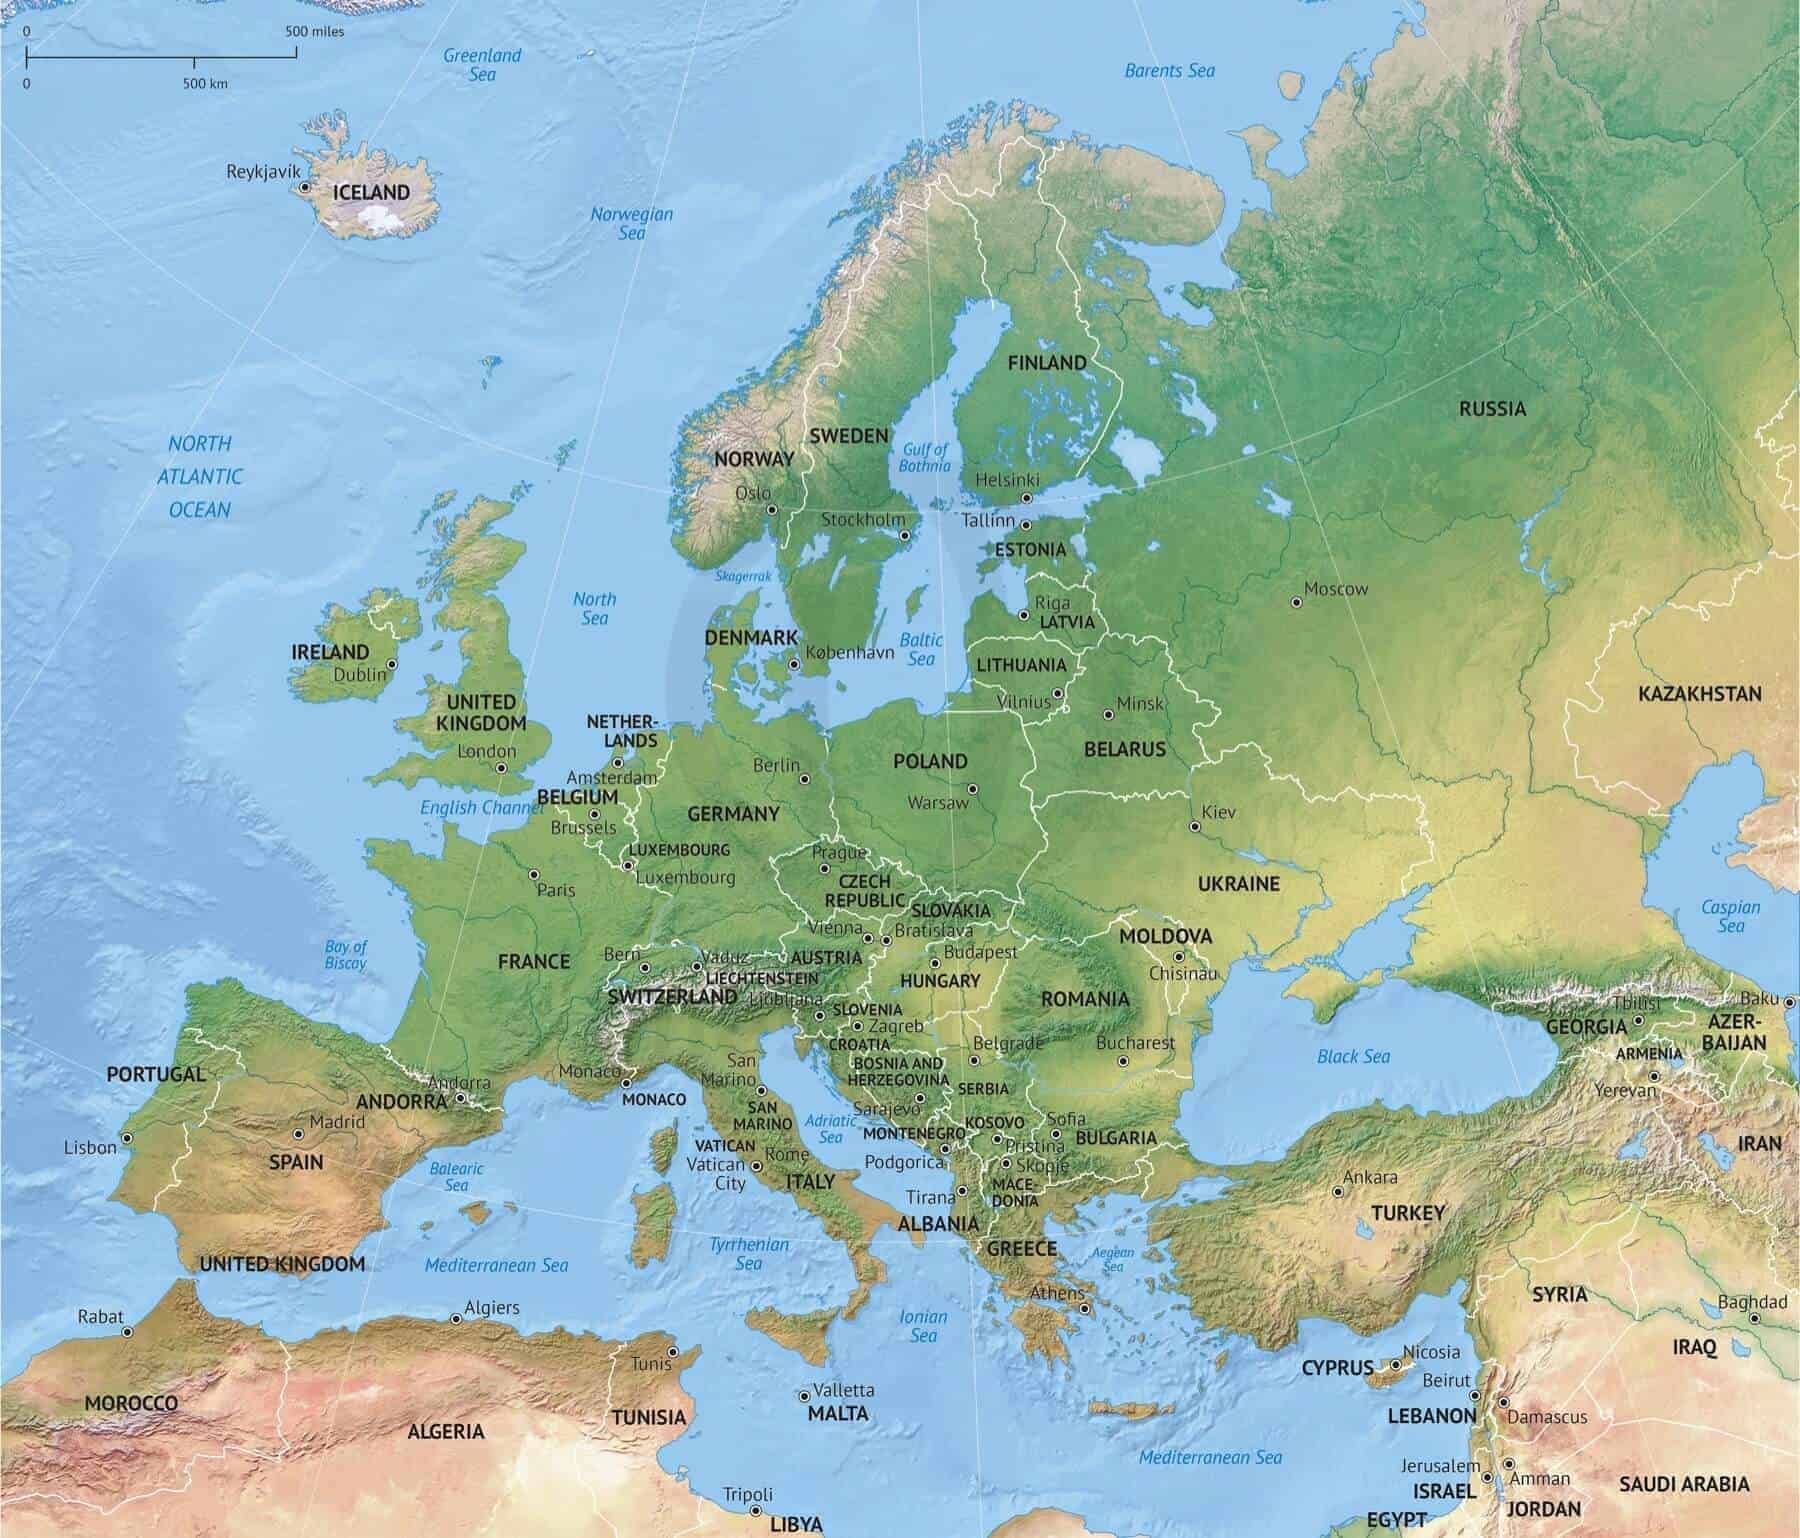
Storage levels across the continent tell a worrying story. European gas inventories are currently trailing their five-year seasonal averages, sitting roughly 70% full as the heating season approaches. Governments wanted 80% or higher. They didn't get it. Maintenance outages in Norway haven't helped either, clipping pipeline inflows just as the system needs every cubic meter it can secure. When domestic piped supply dips, utilities have to replace it with spot LNG. That triggers direct competition with Asian buyers who face their own demand surges as temperatures drop.
The Geography Problem No One Wants to Fix
Energy security sounds like a boardroom buzzword until a single chokepoint blocks millions of barrels and billion-dollar gas shipments. The disruption of flows through Middle Eastern corridors has forced tankers onto longer, more expensive routes around Africa. Longer voyages eat up shipping capacity. Fewer available vessels mean higher freight rates, which translates directly into costlier energy for anyone buying on the spot market.
Industrial powerhouses in Germany and Italy feel this pinch first. Chemistry plants, steel mills, and fertilizer manufacturers operate on razor-thin margins when energy costs spike. If Asian economies aggressively outbid European utilities for spot cargoes, factories face a grim choice: curtail production or absorb input costs that destroy profitability. Many won't survive another winter of double-digit price spikes without deep government intervention.
Why Inventories Are Not Enough This Year
You will hear analysts say that global liquefaction capacity is expanding, pointing to new US and Qatari export projects coming online over the next few years. That is true on paper. In practice, future capacity doesn't heat homes today.
- U.S. dry gas production continues to scale, but domestic consumption and feedgas demands leave less spare cushion than headline numbers suggest.
- Asian economic demand has rebounded stronger than anticipated, absorbing volumes that might otherwise have flowed westward.
- Spot pricing mechanisms act like a giant vacuum cleaner, pulling cargoes to whichever region flashes the highest bid on any given morning.
This dynamic creates a zero-sum game for winter security. European utilities cannot simply command tankers to dock in Rotterdam or Zeebrugge if Asian buyers are willing to pay a dollar more per mmBtu. Global LNG is a liquid market in the truest sense; it flows straight to the highest wallet.
What Happens When the Cold Snap Hits
If weather forecasts hold true and we experience a mild winter across the Northern Hemisphere, current storage buffers might just hold. Prices will stabilize, and the market will breathe a collective sigh of relief. But weather is notoriously fickle. A single prolonged polar vortex stretching across Northeast Asia and Northern Europe will instantly deplete inventories.
Goldman Sachs and other major desks have already flagged upside risks, warning that European benchmarks could easily climb past €100 per megawatt-hour if supply channels remain choked and cold weather sets in early.
Monitor regional storage draw rates week by week. Watch tanker tracking data for shifts away from the Atlantic basin toward Pacific terminals. If you manage energy-intensive supply chains, lock in fixed-rate contracts now rather than gambling on a spot market primed for sudden shocks. The tug of war has already begun. Make sure your balance sheet is ready for the pull.