The world spent decades bracing for cheap plastic widgets, knock-off electronics, and mass-produced textiles flooding global shipping lanes. Economists called that the first wave. Then came the second, dominated by electric vehicles, lithium batteries, and solar panels that terrified legacy manufacturers in Detroit and Wolfsburg. But pay attention to what is building on factory floors right now, because the third iteration is going to hit international markets completely differently.
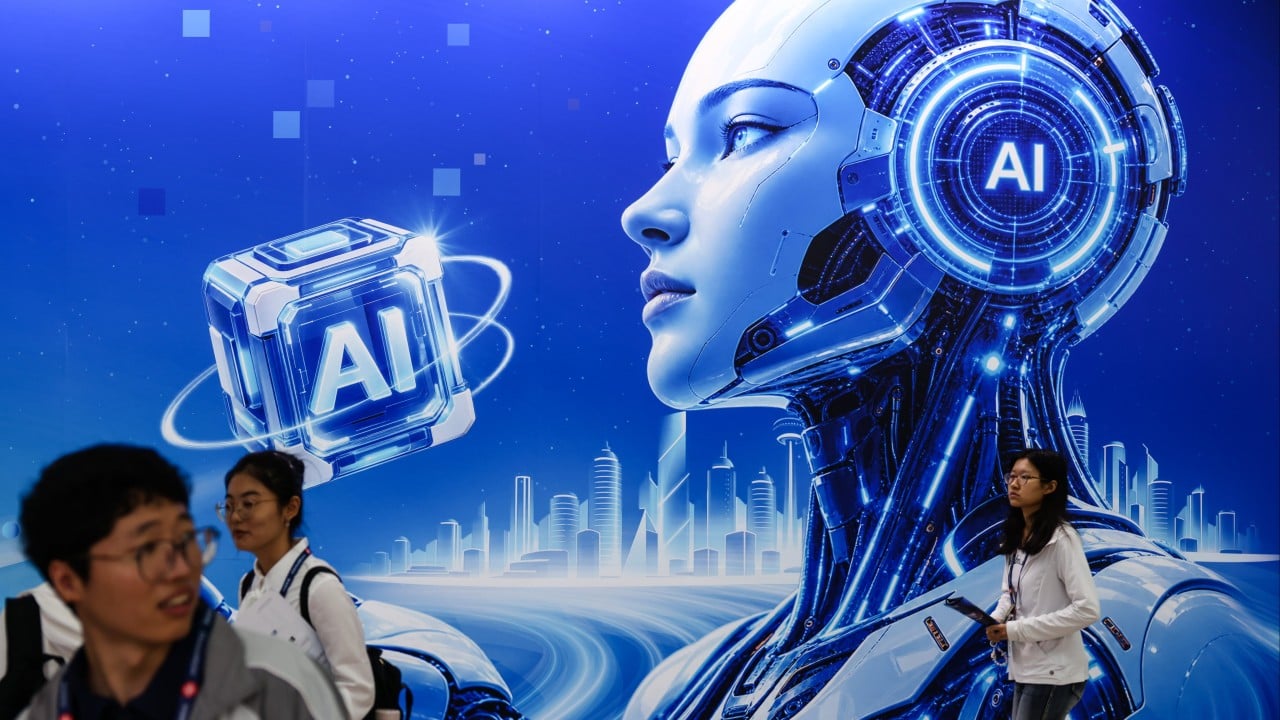
Experts like Alicia Garcia-Herrero, chief economist for Asia-Pacific at Natixis and a senior fellow at Bruegel, point straight toward artificial intelligence, advanced biotechnology, and automated robotics as the core drivers of this upcoming shift. Forget physical consumer goods for a second. We are talking about high-value software, hardware, cloud architecture, and physical AI systems that will challenge Western dominance where it hurts most—at the bleeding edge of innovation.
Why the Previous Trade Waves Missed the Real Shift
If you look back at how global trade evolved over the last thirty years, the trajectory was straightforward. China built its economy on assembling low-cost consumer goods, scaling up labor-intensive manufacturing until it captured an undeniable slice of world commerce. When labor costs rose and automation crept in, the country pivoted upstream into green tech.
That second wave caught policymakers off guard. Western governments watched helplessly as subsidized solar cells and electric cars undercut domestic alternatives by massive margins.
Yet, treating the upcoming wave as a mere repeat of the electric vehicle story is a mistake. The third phase won't rely solely on shipping physical items across oceans in giant container ships. It will blend cloud infrastructure, open-weight models, and embodied robotics into a package that alters how global enterprises operate.
The Anatomy of the New Export Wave
Beijing's strategy has shifted from basic hardware assembly to cultivating indigenous tech stacks. Domestic companies are building competitive AI processors, large-scale language models, and specialized software ecosystems.
Once local demand scales and stabilizes, these digital assets and automated physical systems are primed for export.
Consider what happens when you combine advanced cloud services with humanoid and industrial machinery. Alicia Garcia-Herrero highlighted this exact point during a recent Peterson Institute for International Economics virtual event, noting that the coming shock involving embodied AI and industrial automation will dwarf what we saw with traditional manufacturing.
We aren't just talking about a cheaper version of a Western chatbot. We are looking at bundled data centre solutions, specialized chip architectures like those emerging from firms expanding into physical AI, and industrial robots capable of dropping straight into automated factories worldwide.
Where Biotech and Robotics Intersect with Global Markets
The hardware-software integration extends past basic automation into life sciences. Biotechnology is rapidly digitizing, moving from a slow, empirical trial-and-error laboratory science into a high-throughput computational discipline.
When you pair automated laboratory robotics with massive domestic genomics data sets, the speed of discovery accelerates exponentially.
Western markets often lean heavily on stringent regulatory moats and legacy pharmaceutical pipelines to maintain pricing power. But if automated research platforms and biotech solutions can slash development costs overseas, global pricing pressures will follow.
The Geopolitical Tightrope and Regulatory Walls
Naturally, Western capitals aren't sitting still. Export controls, semiconductor restrictions, and tariff barriers have become standard tools of economic statecraft.
Ironically, these very restrictions have often backfired or accelerated domestic substitution inside China. Instead of crushing innovation, external pressure has forced local enterprises to build self-reliant hardware and software loops.
Yeling Tan, a professor of public policy at the University of Oxford and senior fellow at the Peterson Institute, points out that navigating this friction requires extraordinary diplomatic courage. Finding a sustainable path forward is a narrow corridor. Both sides are currently locked in a technological race where economic statecraft frequently overrides open-market logic.
Yet, market gravity has a funny way of bypassing political barricades. If a developing nation or an enterprise in Europe can license a high-performing open-weight model or purchase an efficient industrial automation suite at a fraction of Western costs, economic incentives usually win out over diplomatic warnings.
What This Means for Global Competitiveness
If you are running a business or formulating tech strategy today, ignoring these shifting dynamics is professional negligence. The competition is no longer about who can manufacture a widget for fifty cents less. It is about who owns the foundational layers of physical AI, who sets the standards for industrial robotics, and who provides the underlying cloud capacity for enterprise automation.
Look at how major cloud providers and tech firms are already positioning their infrastructure globally, setting up regional data centers to support real-world artificial intelligence deployments. The infrastructure is being laid right now.
Prepare your organization by auditing your reliance on legacy vendor ecosystems and keeping a close eye on how open-source and alternative tech stacks mature over the next twenty-four months. The shift is already underway.