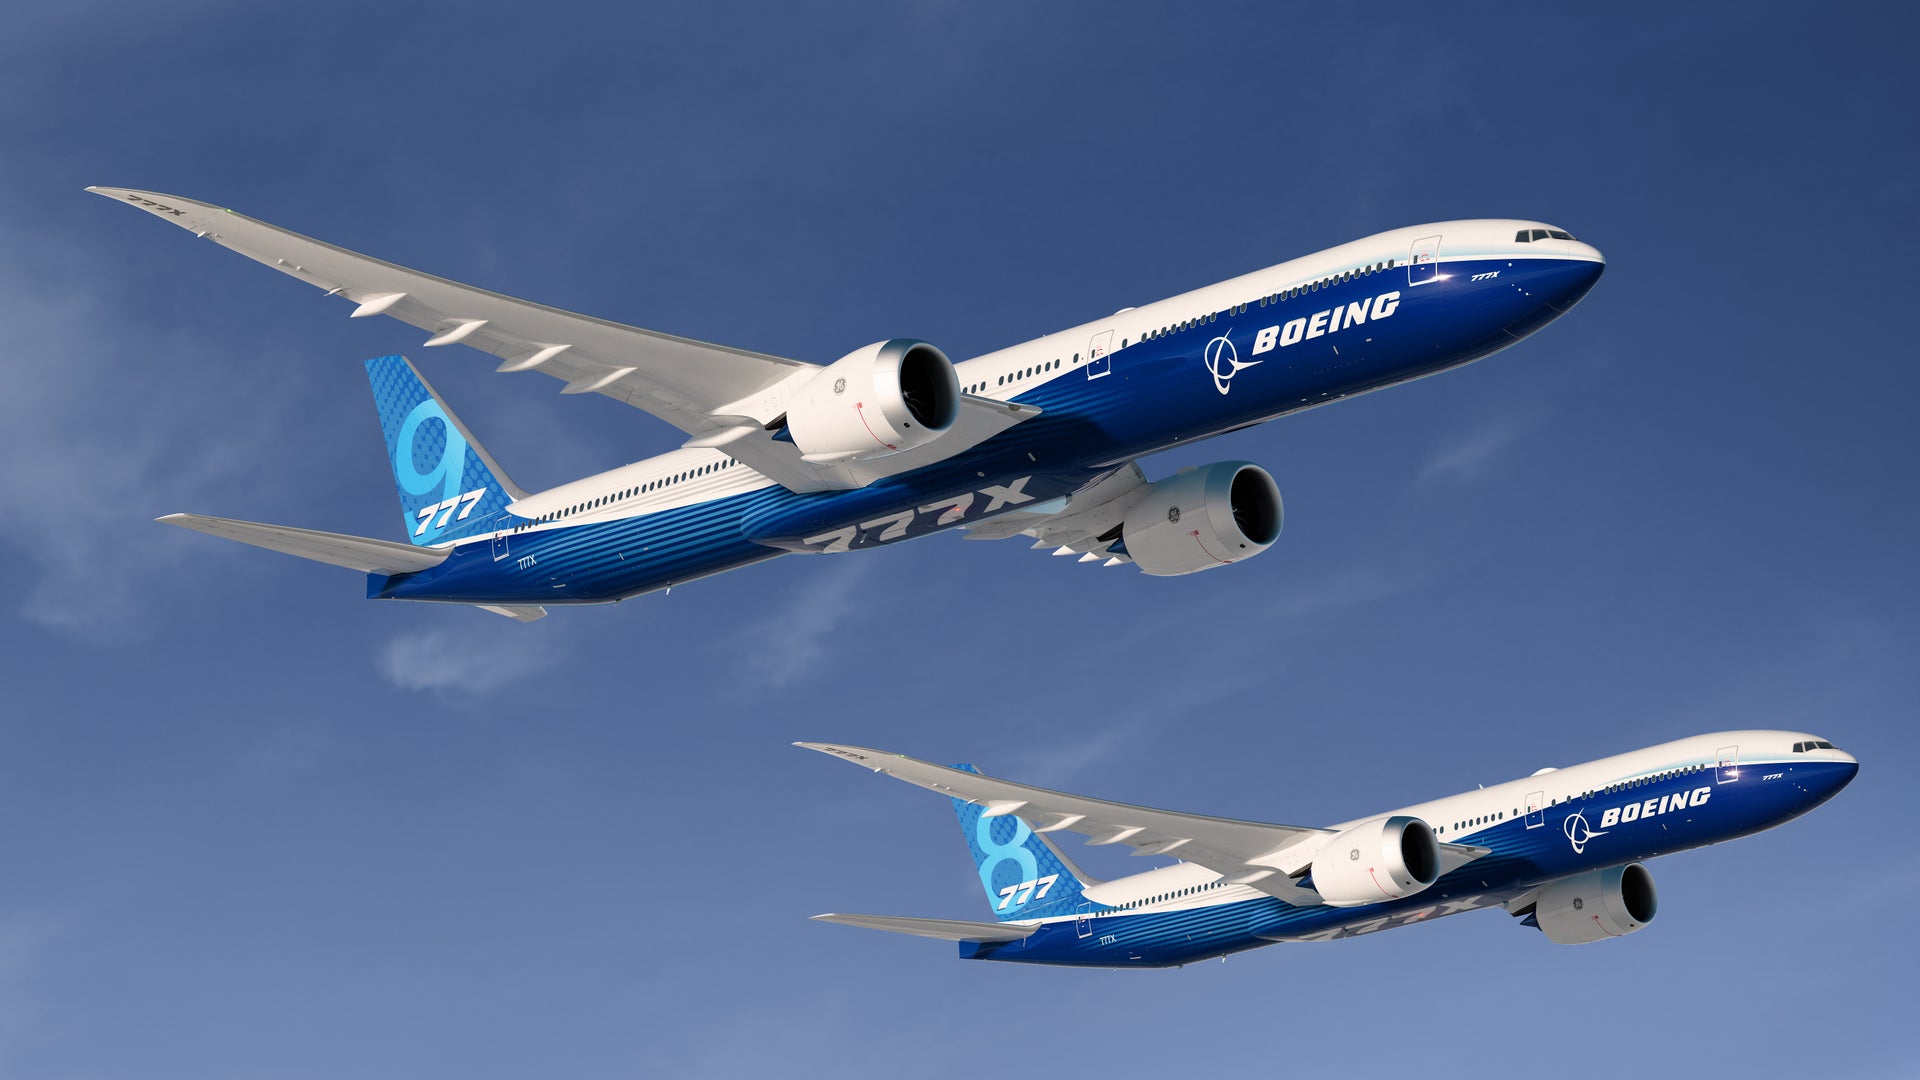
Wall Street hates surprises. Boeing delivered another brutal dose of reality, sending its stock price plummeting by nearly ten percent in a single trading session. The aerospace giant admitted it will miss its heavily publicized 2026 delivery targets for its cash-cow single-aisle aircraft, shattering confidence in an already fragile corporate recovery. If you thought the company was finally turning the corner after years of manufacturing scandals and intense regulatory scrutiny, today's announcement proves otherwise.
The Reality Behind the 737 Delivery Slash
Boeing executives confirmed that the planemaker will fall short of its ambitious goal to push out about 500 737 jets this year. Instead of stabilizing its production rate at 47 jets per month by the summer of 2026, management pushed that milestone out to early 2027. Why? Because chasing speed over stability simply does not work anymore. For an alternative look, see: this related article.
When you rush assembly lines to satisfy frustrated airline customers, quality control inevitably slips. Boeing has learned this lesson the hard way. Slowing down the pace to inspect every rivet, fix factory floor bottlenecks, and appease federal regulators is the right operational move. Yet, equity markets punished the stock because lower production means delayed cash flow. Wall Street wanted immediate returns, but manufacturing multi-million-dollar commercial airliners demands caution over quarterly earnings beats.
Financial Strain and the Free Cash Flow Problem
The delivery slump hits the balance sheet where it hurts most. Free cash flow targets have slipped drastically, with the company now projecting about $3 billion for next year—a full year later than previous estimates and far below the $5.5 billion consensus predicted by LSEG. Related analysis regarding this has been shared by Financial Times.
Third-quarter numbers tell a mixed story. Revenue ticked up to $24.2 billion, and the core loss narrowed to 34 cents a share, showing that revenue is flowing in. The massive record backlog of $745.4 billion proves that airlines still want Boeing planes. Airlines simply do not have many other places to go. Airbus is practically sold out for the decade. Yet, holding a massive backlog means nothing if you cannot physically roll planes out of the factory doors in Renton and Everett.
Defense Resilience Versus Commercial Headwinds
It is easy to paint Boeing with a single brush of doom, but commercial aviation woes obscure a surprisingly resilient defense sector. Defense revenue rose fifteen percent to hit $7.9 billion, while the defense backlog climbed to a record $101 billion.
Defense and space segments have their own execution hurdles and fixed-price contract headaches, but they are currently acting as a financial shock absorber. When commercial jet production stalls out, government contracts keep the lights on and the assembly lines funded. Investors often forget that Boeing is a defense prime contractor just as much as it is a commercial planemaker.
What Comes Next for the Stock and the Sector
The sharp sell-off reflects deep-seated fatigue among institutional investors. They are tired of waiting for a clean operational slate. Every time Boeing seems ready to accelerate, a fresh supply chain snag, software glitch, or regulatory bottleneck drags them backward.
If you are looking at Boeing shares right now, do not try to catch a falling knife based purely on dips. Watch the monthly delivery data instead of corporate forecasts. Until factory output consistently hits stable targets month after month without sudden pauses, the stock will remain range-bound in high volatility.